 kritika
(C): X
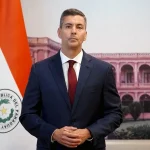
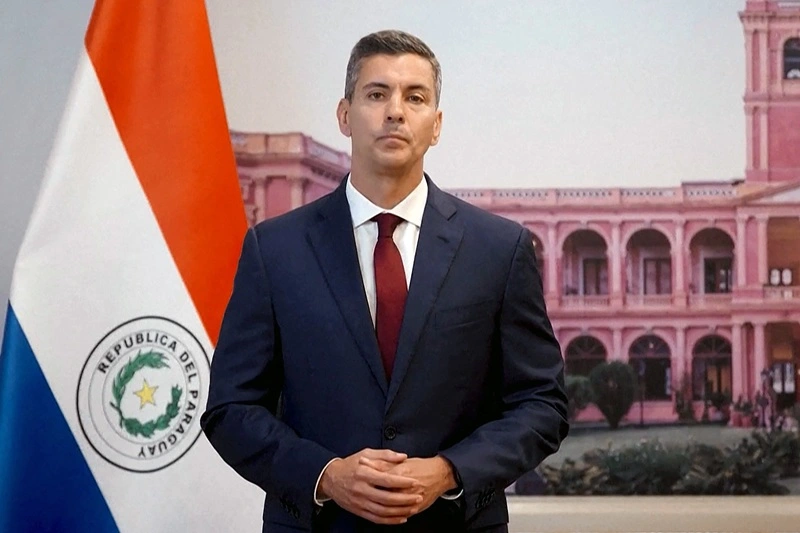
The Paraguay banking crisis went from regulatory notice to national emergency in days. The central bank’s intervention in digital lender Ueno left millions of customers unable to access their accounts; the central bank chief resigned, and On November 5, 2026, President Santiago Peña resigned. An interesting challenge arises from the situation of the Ueno Bank financial meltdown: How did this young fintech venture expand to become large enough for its collapse to have national implications?
Key Highlights
- The central bank had to intervene when Ueno failed to meet the capital adequacy requirement.
- Reach: Approximately 3 million customers in a country with 6.5 million people.
- Public money: About $850 million in public money, including state institutions and pension money.
- Arrest warrants were issued for eight Ueno executives, who later surrendered.
- Markets: The guarani fell nearly 5% to 6,490 per dollar at the close.
- Politics: Peña has stepped down; his successor is Vice President Pedro Alliana.
From Niche Fintech to Market Dominance
Ueno began as a niche fintech and blossomed into a mid-sized bank. Ueno Bank’s market dominance, with almost half the population as customers, meant that its health was never a private matter. Its Ueno Bank growth strategy and Ueno Bank business expansion have arrived at the stage of managing public funds.
Why Did Ueno Become Too Big to Fail
Banks are too big to fail when their failure would cause much more damage to people than to their shareholders. Ueno was that kind of guy. In Paraguay banks, one failure threatened to spread because households and state institutions both depended on it, which is a textbook case of systemic risk. The risk of concentration in the banking sector is that it puts so many savers and so much of the public’s money into one lender’s hands. And that’s the heart of the risk big financial institutions pose: it limits the choices regulators have.
Central Bank Violation of Solvency and Supervision
The turning point came when the central bank said that Ueno had breached minimum solvency requirements. Detailed figures of Ueno Bank assets and liabilities were not included in the first reports. The intervention has pressured oversight by Paraguay’s central bank. The crucial question is whether the lender’s growth rate outpaced Paraguay’s banking regulations and banking supervision and regulation.
Political Fallout and Government Intervention
Peña has past ties to Grupo Vazquez, the group that owned Ueno until March 2025. He said he sold his stake that month and played no improper role. Opposition lawmakers charged him with conflicts of interest, misuse of pension funds and shielding the bank from oversight. He denies wrongdoing. He lost backing within his Colorado Party and stepped down just hours before impeachment proceedings moved forward. Any government intervention in Ueno Bank will now be judged against this backdrop, with the risks of bank bailouts including public cost and moral hazard.
Economic Stability and Market Impact
Sovereign bond prices tumbled, and the guarani slipped past 6,500 to the dollar. The Paraguayan Banking Crisis serves as a test for the economic stability of Paraguay as well as its financial market vulnerabilities. Paraguay was one of South America’s more stable economies, so the episode feeds into wider Latin American banking crisis concerns.
Next Steps
For customers, the top priority is getting access to their money again, and clear rules about deposit protection in Paraguay will be important for restoring confidence. Now, the prospects for Paraguay’s banking industry depend on better oversight and tighter limits on the amount of public money a single bank can hold. The lesson from the Paraguay banking crisis is that rules should be forward-looking, not reactive.
Banking Shake-Ups: Who Could Be Affected Next?
1. Which Banking Jobs Could Disappear Next?
Find out how HSBC’s proposed adviser cuts could reshape banking employment opportunities.
2. Will a Five-Day Banking Week Change Everything?
Explore how the proposed banking week could affect working hours, holidays and employee salaries.
3. Will SBI Strike Disrupt Banking Services?
Check out how the May 25–26 strike could affect branches, cheque processing and internet banking.
4. Could IDBI Employees Lose Job Security?
Uncover how IDBI Bank’s proposed privatisation could affect employees despite their role in its financial recovery.
5. Are NatWest Employees Facing More Pressure?
Discover how the removal of 1,400 roles could increase workloads for remaining bank employees.